All Categories
Featured


Essential Local Business Medical Insurance Updates
Table of Contents
If a group life ins prepare fails these tests, key employees might lose the tax exclusion, making their entire protection quantity taxable. Penalties for non compliance can be substantial. If a business's group life ins prepare just covers executives or offers them much better rates, the IRS might reclassify the benefit, resulting in extra taxes owed.
Each state may impose additional guidelines affecting group life ins. Typical requirements include minimum protection requirements, mandated policy disclosures, and recipient securities. Some states even require continuation of group life ins protection after employment ends, beyond what federal COBRA laws provide. Employers must examine their group life ins policies for compliance with state guidelines.
Keeping up with these requireds prevents legal disputes and ensures benefit connection for staff. Compliance with HIPAA and similar personal privacy laws is vital to safeguard employee information.
Best Dental and Vision Benefits for Staff
HR teams using safe online platforms can rapidly produce records for audits or claims. Correct paperwork supports regulatory compliance and employee rely on the group life ins program. Creating an effective group life ins prepare begins with understanding your labor force and aligning protection with organizational objectives. A thoughtful method ensures you maximize worth, assistance staff member well-being, and maintain compliance as you build a competitive advantages plan.
Local Insurance ExpertsUsage anonymous studies or focus groups to find what they value most in group life ins, such as mobility, supplemental coverage, or dependent choices. Evaluation your spending plan and criteria against industry norms. Think about both the cost of base protection and any additional functions, balancing monetary constraints with competitive offerings. For instance, if a survey exposes strong interest in buy-up options, designate funds accordingly.
Picking a provider for group life ins involves more than just comparing premiums. Evaluate insurance providers based upon monetary stability, claims processing speed, and client service track record. Try to find carriers providing strategy functions that match your workforce, such as accelerated survivor benefit, waiver of premium, or accidental death and dismemberment riders.
Best Dental and Vision Insurance for Staff
Choose whether your group life ins plan will be employer-paid, voluntary, or a hybrid. Employer-paid protection typically enhances participation, while voluntary protection enables employees to purchase additional defense for themselves or household.
Reliable education leads to notified decisions and higher enrollment rates, making sure that your group life ins prepare is both valued and utilized by your group. Efficient administration is key to a smooth group life ins experience.
A streamlined claims procedure, with clear documents requirements and timely support, develops trust among employees. Routinely review administrative treatments to stay certified and responsive, keeping your group life ins prepare operating at peak effectiveness. Display involvement rates, employee feedback, and claims data to gauge the effectiveness of your group life ins plan.
Comprehensive Commercial Insurance and Group Benefit Strategy
Continuous enhancement guarantees your group life ins prepare develops with your labor force, keeping its worth and relevance year after year. Comprehending the strengths and weaknesses of group life ins is essential for employers aiming to use a well-rounded benefits bundle.
Group life ins supplies instant financial defense for employees' families, offering peace of mind in the event of an unexpected loss. Employers can provide this advantage at little or no charge to personnel, making it an extremely valued addition to any compensation plan. The straightforward credentials procedure, with very little medical underwriting, guarantees most workers can enlist without problems.
Many organizations report enhanced recruitment and retention after including group life ins. Some companies have actually earned "finest location to work" acknowledgment due to their robust advantages offerings. Beyond the basic death advantage, group life ins strategies often consist of valuable optional features. Sped up survivor benefit permit workers to access a portion of the payout if diagnosed with a terminal illness, supplying vital financial backing when it's required most.
Maximizing Employee Loyalty through Robust Benefits
Encourage employees to complete recipient types and evaluation coverage choices during open registration. Efficient education results in informed choices and higher enrollment rates, guaranteeing that your group life ins prepare is both valued and used by your team. Efficient administration is crucial to a smooth group life ins experience. Appoint clear functions to HR or benefits groups for dealing with enrollment, payroll reductions, and claims assistance.
A streamlined claims procedure, with clear documentation requirements and timely support, constructs trust amongst staff members. Routinely evaluation administrative treatments to stay compliant and responsive, keeping your group life ins prepare operating at peak efficiency. Monitor involvement rates, staff member feedback, and claims data to determine the effectiveness of your group life ins prepare.
Change coverage amounts, include brand-new features, or improve communication based upon what you discover. For instance, if staff members request greater caps, think about increasing limits in your next renewal cycle. Constant improvement guarantees your group life ins prepare progresses with your labor force, preserving its worth and significance every year. Comprehending the strengths and weak points of group life ins is vital for employers intending to offer a well-rounded advantages package.
Professional Staff Assistance EAP Resource Guidance
Group life ins provides immediate financial security for employees' families, providing comfort in the occasion of an unexpected loss. Companies can deliver this advantage at little or no cost to personnel, making it a highly valued addition to any payment bundle. The uncomplicated certification procedure, with very little medical underwriting, guarantees most staff members can register without issues.
Numerous companies report enhanced recruitment and retention after including group life ins. Beyond the fundamental death benefit, group life ins plans typically include important optional features.

Latest Posts
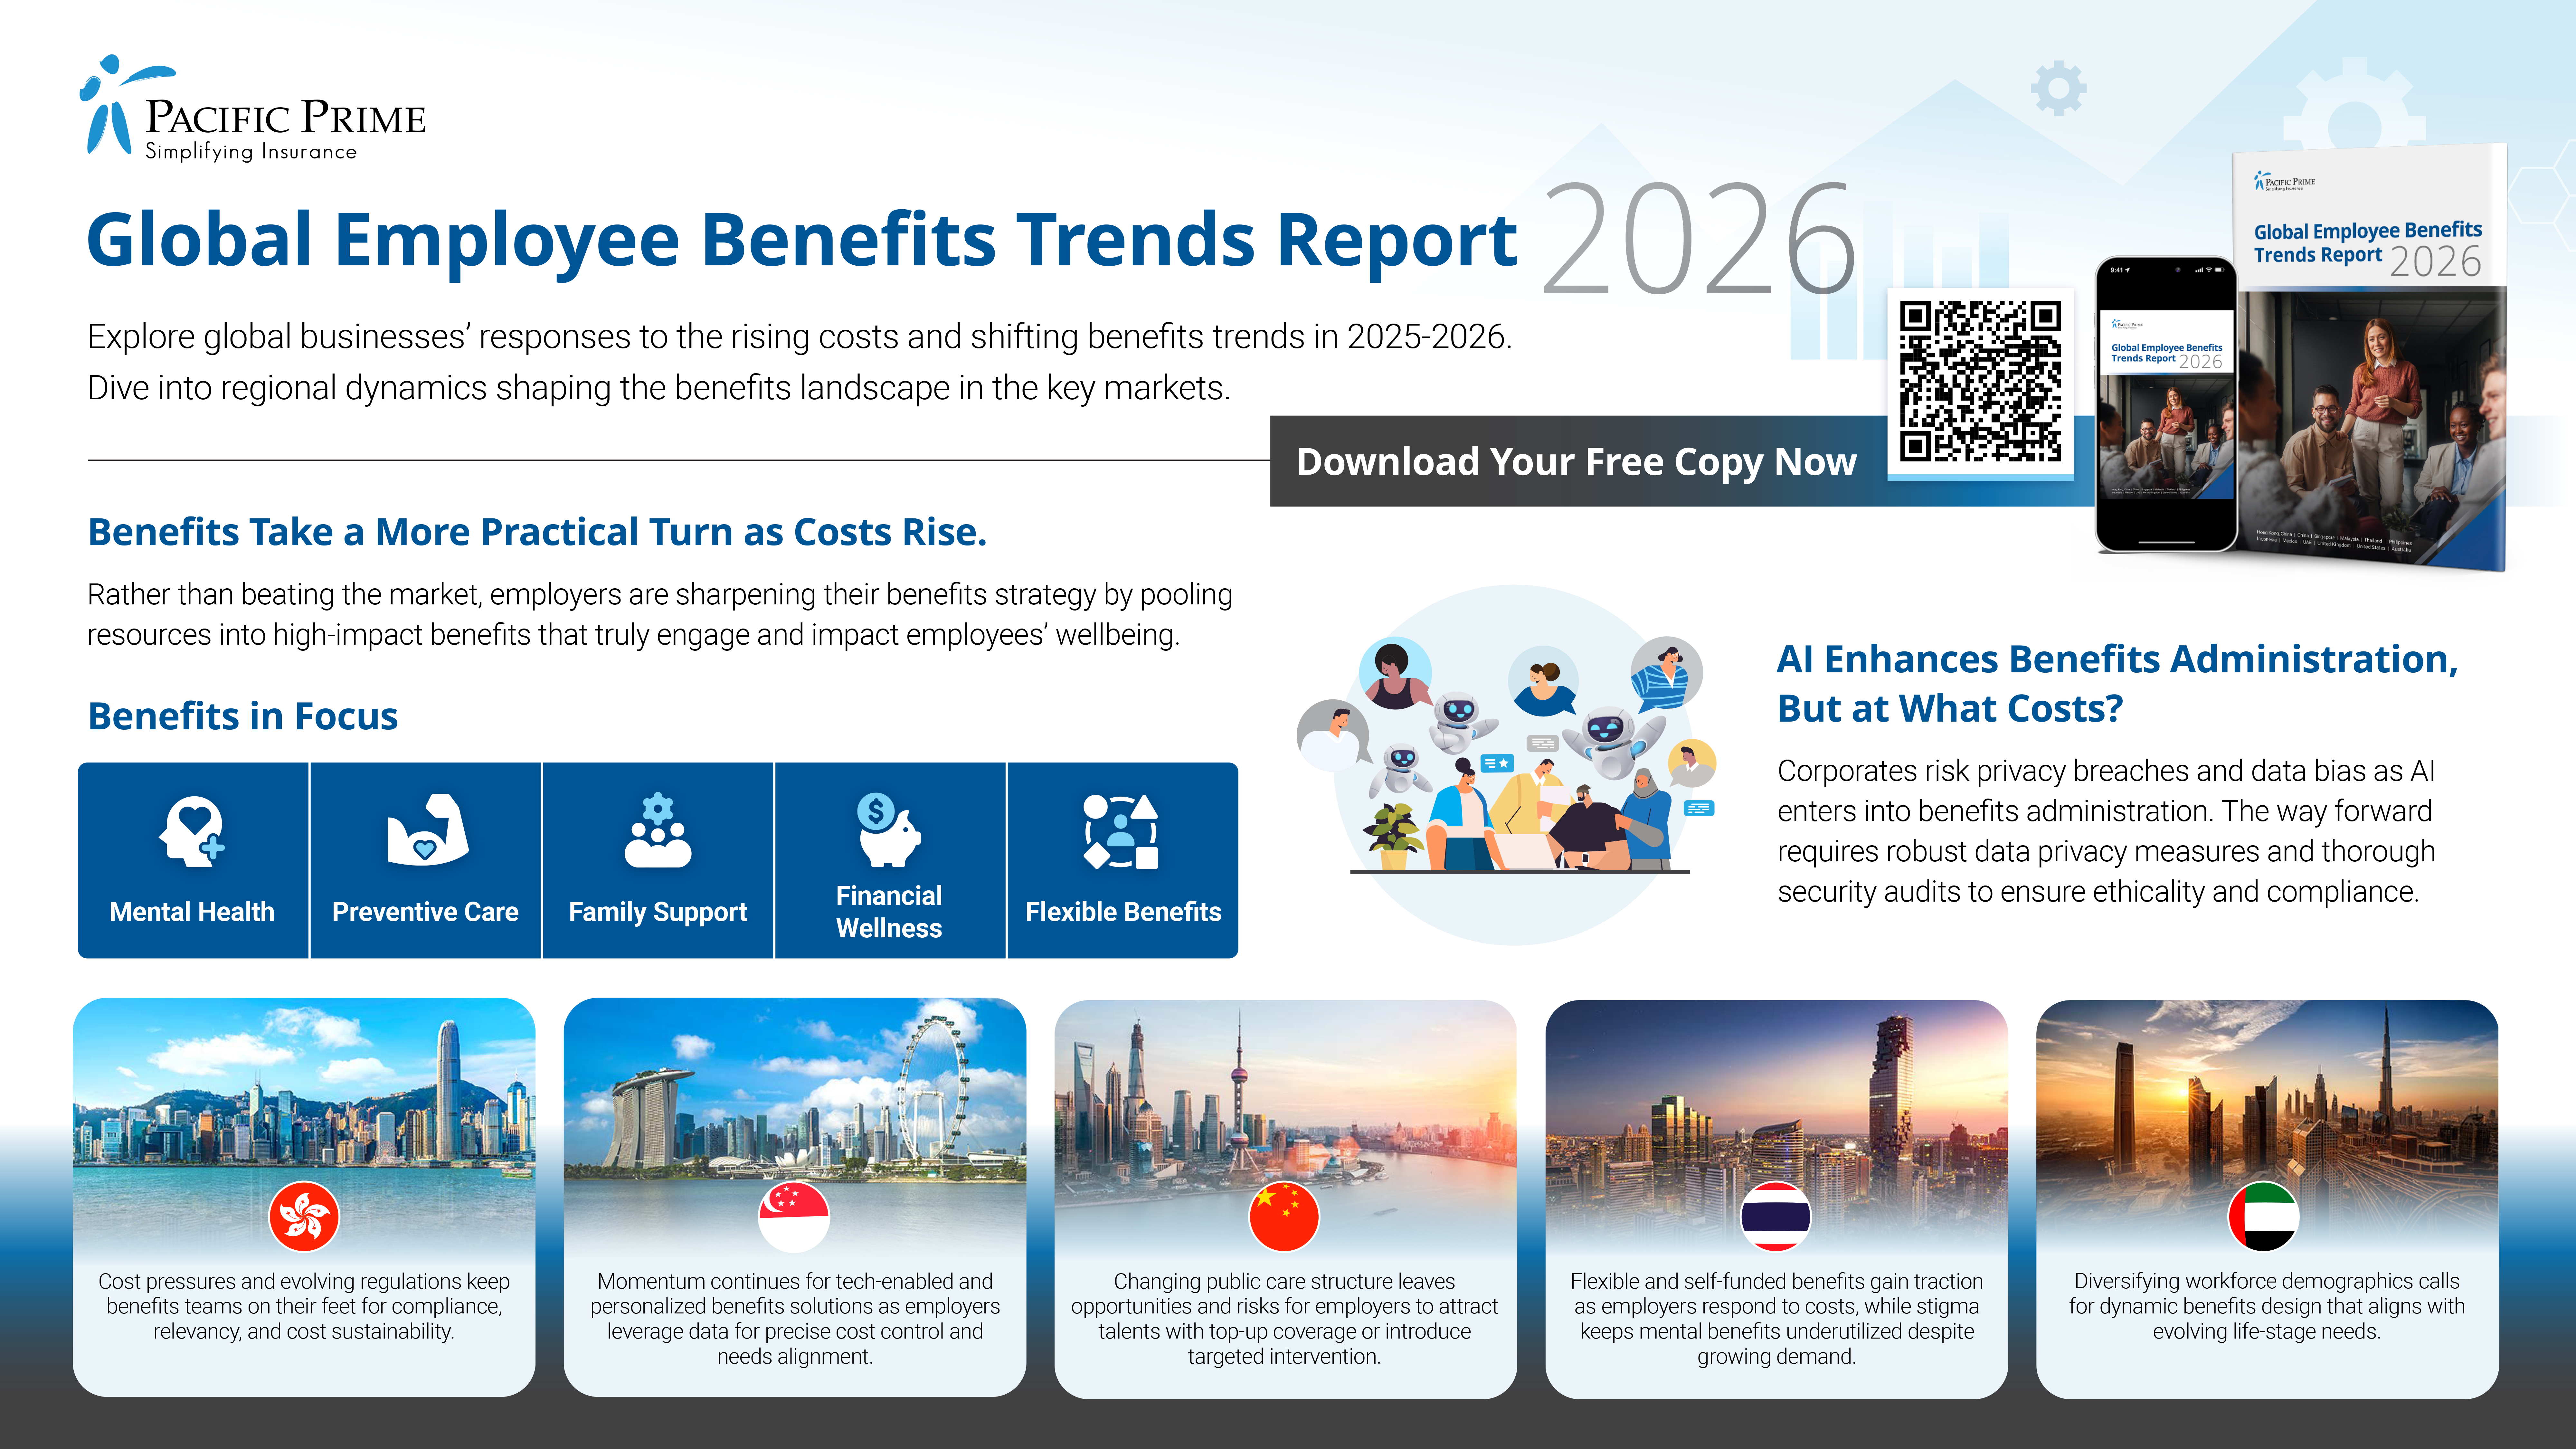
Expense Reduction Strategies for 2026 Benefits

Effective Workplace Health Programs for 2026
Choosing the Best Dental Options